Csquare Shares Fell 11.8% After Short Report; Securities Investigation Followed
A short report on October 22, 2026, preceded a share-price decline and an investigation announcement eight days later. The inquiry focuses on the company’s descriptions of its cash generation and reliance on outside funding.
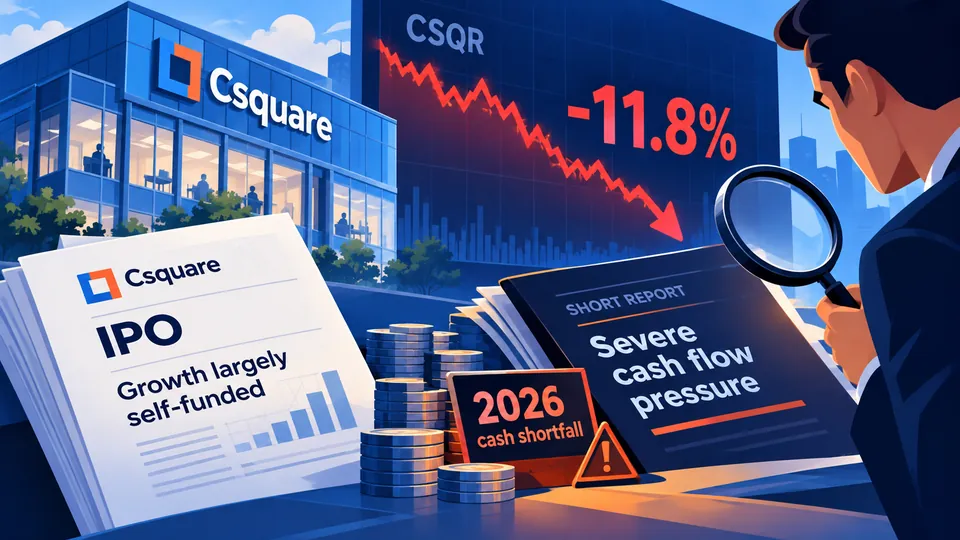
Csquare shares fell over 11.8% after the short report appeared.1
The filings reported $988.4 million in financing inflows for 2025.1
The filings reported $172.0 million in operating cash flow for 2025.1
Story
The cash-flow claims behind the Csquare investigationCsquare shares dropped over 11.8% after a short report appeared on October 22, 2026, marking the immediate market change described in the notice.1 The report came from Keith Dalrymple of Dalrymple Finance and asserted that the company faced serious cash-flow strain and projected shortfalls during 2026.1 On October 30, 2026, Levi & Korsinsky announced an investigation into Csquare securities, placing the earlier report and the company’s disclosures under scrutiny.1 The announcement identifies Csquare, Inc. as a company listed on the New York Stock Exchange under the ticker CSQR.1 The investigation is not described as a finding of wrongdoing; its stated focus is whether securities laws may have been violated through company statements about funding.1
The disclosures now being examined preceded the October short report, and the notice says investors may have bought securities at prices made artificially high by those statements.1 The questions include whether Csquare accurately explained its funding requirements and its dependence on money from outside the business.1 The inquiry also tests statements describing a growth plan intended to fund itself and the company’s assertion that operations produced strong cash generation.1 These issues connect the report’s cash-pressure allegations to earlier company disclosures, but the announcement does not establish that the allegations are true.1 Instead, the announced work concerns the accuracy and completeness of Csquare’s account of how it financed growth and what its operations generated.1
Csquare submitted registration materials to the Securities and Exchange Commission on March 30, 2026, and May 20, 2026.1 In those documents, the company presented its expansion strategy as one that would be financed mostly from within the business.1 A later company filing, its second-quarter 2026 Form 10-Q dated August 10, said the business produced strong cash from operations.1 Those statements form part of the investigation because the announced inquiry asks whether Csquare adequately explained its financing needs and operating cash position.1 The dates show that the registration disclosures and the quarterly report both came before the October short report identified in the notice.1
The filing figures distinguish money raised through financing from cash produced by operations: for 2025, the respective amounts were $988.4 million and $172.0 million.1 The financing total was substantially larger than the operating-cash figure, although the two amounts describe different sources of cash rather than interchangeable measures.1 In the first quarter of 2026, operating cash flow was negative $18.3 million, reversing the positive operating amount reported for 2025.1 That quarterly result is distinct from the six-month comparison in the second-quarter report, which recorded a 49% fall from $65.5 million to $33.6 million.1 The notice also reports six-month interest expense of $181.2 million, a separate figure from cash flow and financing inflows.1
Together, the reported amounts describe several different aspects of the company’s finances: operating cash flow, financing received, and interest expense.1 The negative first-quarter operating figure contrasts with the positive 2025 operating amount, while the second-quarter filing’s stated comparison shows a decline between its two cash-flow amounts.1 The $988.4 million financing inflow for 2025 is not itself evidence of cash generated by operations; the filing reports those categories separately.1 The investigation’s stated question is whether the company sufficiently described its reliance on outside financing alongside its claims about self-funded growth and operating cash.1 The figures provide context for that inquiry, but the announcement does not say they alone resolve whether any statement was misleading.1
The notice concerns people who purchased CSQR securities and experienced financial losses; possible eligibility depends on when they bought and on records of those losses.1 Someone who has already sold may still be included for consideration if the person bought the securities and later sold them at a loss.1 Thus, eligibility is not limited by the notice to people who still own shares, though the stated purchase and loss conditions remain relevant.1 The notice does not provide a single purchase-date range or a guaranteed outcome for an investor who submits information.1 Instead, it describes eligibility as dependent on individual transaction timing and documented financial results.1
Investors considering a review may collect brokerage statements or other records showing when they bought, how many shares they acquired, and what prices they paid.1 If they later sold, the relevant records may also include the sale date and the price received.1 Those details allow the review to consider purchase timing and any subsequent loss, the factors the notice associates with potential eligibility.1 The firm says people may send their information for an assessment that carries no charge and no obligation.1 It also says no immediate step is needed to preserve the possibility of joining the investigation.1
Submitting information for review does not require an advance payment, according to the notice.1 If a legal action results, any lawyers’ fees and expenses would be subject to approval by a court.1 Levi & Korsinsky said participation in the investigation would not require investors to appear in court or give depositions.1 The notice names Joseph E. Levi, Esq. and Ed Korsinsky, Esq. as contacts for people seeking information.1 These provisions describe the announced review process; they do not change the notice’s conditions concerning purchase dates and documented losses.1
The sequence begins with company disclosures in March, May, and August 2026, continues with the October 22 short report and share decline, and reaches the investigation announcement on October 30.1 The short report alleged cash-flow pressure and projected 2026 shortfalls, while the investigation announcement examines whether earlier company statements about financing and operations were materially misleading.1 The company’s described self-funded strategy and strong-operating-cash statement are central because the investigation specifically includes those descriptions among the statements under review.1 The reported cash figures differ by period and category, so the financing inflow, operating amounts, and interest expense should not be treated as one measure.1 For investors, the announcement sets out a process for submitting transaction information while leaving any individual eligibility assessment dependent on timing and losses.1
The announcement therefore describes an investigation into disclosure and potential securities-law issues, not a conclusion that Csquare violated the law.1 Its central comparison is between the company’s claims about internally funded growth and strong operational cash generation, and the financial disclosures cited in the notice.1 The short report preceded the investigation, but the notice presents its allegations as the trigger for scrutiny rather than as an adjudicated account of the company’s finances.1 Investors who believe they may qualify can provide purchase and sale records for review, with no upfront submission charge and no immediate action required to remain eligible.1 The outcome of the investigation and the eligibility of any particular investor are not specified in the announcement.1
Structure
Who is connected to whom- 1Csquare
- operates in →Fact
- located in →Fact
- owns →Fact
- operates in →Fact
- operates in →Fact
History
How it came to this- March 30, 2026Registration filing submittedCsquare submitted a registration filing to the SEC and described its growth strategy as designed to be largely self-funded.
- May 20, 2026Further registration filing submittedCsquare submitted another registration filing to the SEC; the filings described its growth strategy as designed to be largely self-funded.
- August 10, 2026Second-quarter Form 10-QThe filing stated that the business generates strong cash flows from operations and reported a 49% fall in operating cash flow, from $65.5 million to $33.6 million.
- October 22, 2026Short report and share declineKeith Dalrymple of Dalrymple Finance published a report alleging cash-flow pressure and projected 2026 shortfalls; Csquare shares fell over 11.8%.
- October 30, 2026Investigation announcedLevi & Korsinsky announced an investigation into Csquare securities.
- Nowover 11.8% Csquare share decline after short report
Impact
Spreading outward, level by level- Level 1Disclosure questions
The investigation examines potential securities-law violations and whether Csquare adequately described its reliance on outside financing, funding needs, and statements about self-funded growth and strong operating cash flow.1
Fact - Level 2Potential investor eligibility
Investors who bought CSQR securities and suffered financial losses may be eligible, depending on purchase dates and documented losses; people who sold may still be considered if they bought and sold at a loss.1
Fact - Level 3Records for review
Brokerage records can show purchase dates, share quantities, prices paid, and any later sale dates and prices.1
Fact - Level 4Context for the inquiry
The reported cash-flow figures give context for why the investigation focuses on statements about self-funding and operating cash, while distinguishing operating cash flow from outside financing.
Analysis
Sources
What each source supportsWritten by AI from the sources listed below: every fact was checked word for word against its source, and inference is marked apart. How we write