ESMA adds five new legitimate interests for delayed disclosure under MAR
The European Securities and Markets Authority has updated its Market Abuse Regulation guidelines, expanding the reasons issuers may postpone publishing inside information and removing provisions for protracted processes. The changes take effect upon publication on ESMA’s website in all EU languages.
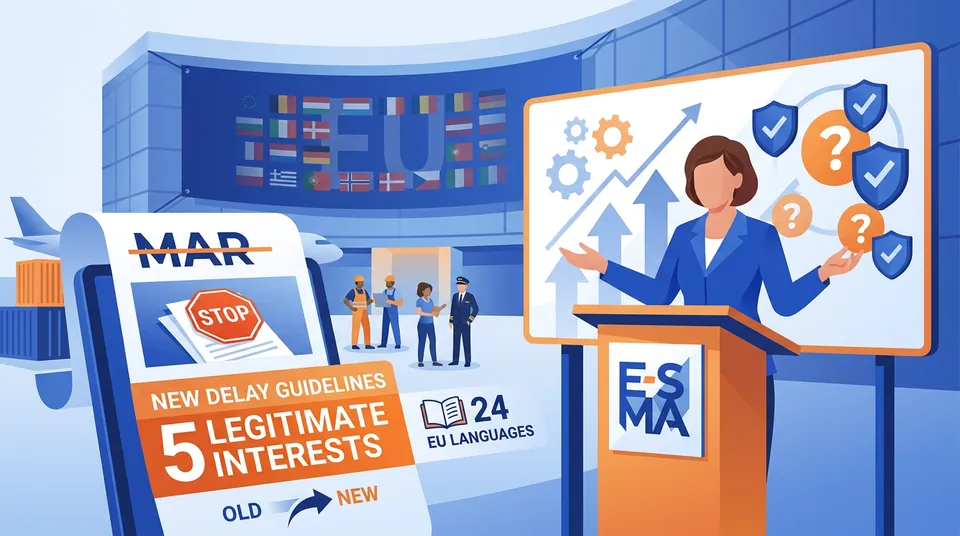
ESMA added five legitimate-interest grounds for delaying public disclosure.1
From June 2026, issuers no longer need to disclose information about protracted processes before those processes are complete.1
The revised guidelines apply when published on ESMA’s website in all 24 official EU languages.1
Story
Updated MAR guidelines expand permissible delays in inside‑information disclosureESMA has completed its review and issued revised guidelines on the timing of inside‑information disclosure under the Market Abuse Regulation.1 The new rules introduce five additional legitimate interests that may justify postponing public release of such information.1 These additions sit alongside the existing framework that already permits delays when certain public‑interest considerations arise.1 The update also eliminates the previous allowance for delays linked to protracted processes.1 By adding clearer categories, the guidance helps issuers assess whether a delay is truly justified under the law.1 The removal of the protracted‑process justification reflects ESMA’s view that the newer timing rules already address that scenario.1 Overall, the changes aim to balance market transparency with legitimate business needs.1
Under MAR, issuers are required to disclose inside information as promptly as possible to keep markets informed and deter insider trading.1 However, the regulation already recognized that immediate publication may sometimes conflict with other legitimate concerns.1 The revised guidance clarifies that such conflicts can now be addressed through the newly defined categories.1 The change does not alter the fundamental duty to disclose as soon as practicable, but it refines the circumstances where a short postponement is acceptable.1 Issuers must still document the reason for any delay to demonstrate compliance with MAR.1 The new categories provide a concrete checklist that can be referenced in internal compliance reports.1 This structured approach reduces the risk of arbitrary or unjustified postponements.1
One of the new permissible interests is a request from a public authority that the issuer refrain from publishing the information.1 Such a request may arise in contexts where disclosure could interfere with regulatory investigations or other official actions.1 Another category allows a delay when the issuer needs to gather additional data to enable market participants to assess the information correctly.1 This provision acknowledges that incomplete data could mislead investors and distort market pricing.1 Collecting the extra information often involves coordination with auditors, legal counsel, or third‑party experts.1 By postponing until the data set is complete, issuers help ensure that price formation reflects the full picture.1 The rule also protects investors from reacting to partial or speculative disclosures.1
A further legitimate interest concerns the risk of losing a business opportunity if sensitive commercial details become public prematurely.1 The guidance recognises that premature disclosure could erode competitive advantage and affect transaction outcomes.1 Delays are also permitted when the appointment of a governing‑body member or key manager might be jeopardised by early disclosure.1 This reflects the importance of ensuring that leadership changes are not disrupted by market reactions to undisclosed information.1 Such appointments often involve confidential negotiations that could be compromised by a sudden market move.1 Allowing a brief postponement helps preserve the integrity of the selection process.1 It also reduces the chance that share price volatility could influence board decisions.1
The final new category addresses situations where disclosing information about a sister company within the same corporate group would directly prejudice the issuer.1 In such cases, a delay helps preserve the effectiveness of coordinated disclosures across the group.1 These five additions collectively broaden the scope of legitimate interests while maintaining the overarching goal of market transparency.1 Coordinated timing ensures that investors receive a balanced view of the group’s overall position.1 It also prevents a scenario where one entity’s disclosure unintentionally harms another within the same group.1 The rule therefore supports both fair competition and investor confidence.1
Since June 2026, issuers have been exempt from the requirement to disclose inside information related to protracted processes before those processes conclude.1 Accordingly, the revised guidelines remove the earlier legitimate‑interest justification tied to such prolonged procedures.1 This removal simplifies the framework by eliminating a category that had become less relevant under the newer disclosure timing rules.1 Issuers no longer need to assess whether a protracted‑process delay fits within the legitimate‑interest test.1 Because issuers no longer have to disclose this information before the processes conclude, ESMA removed the related legitimate-interest category from its guidelines.1 It also aligns the guidelines with the practical reality that long‑running projects often have uncertain outcomes.1
The updated guidelines will take effect on the day they are posted on ESMA’s website, and they will be available in all 24 official EU languages.1 This immediate applicability ensures that market participants can align their disclosure practices without delay.1 Issuers across the European Union will need to adjust internal procedures to incorporate the new legitimate‑interest categories.1 Compliance teams will likely update their checklists and training modules to reflect the five new interests.1 Legal departments must also review existing disclosure policies to ensure they no longer reference the removed protracted‑process justification.1 The multilingual publication guarantees that all market participants, regardless of language, receive the same guidance simultaneously.1
The changes affect any listed company or other issuer subject to MAR, as well as their advisors and compliance teams responsible for disclosure decisions.1 By clarifying when a delay is permissible, the guidelines aim to reduce uncertainty for these stakeholders.1 The revisions also provide a clearer basis for supervisory authorities to assess whether a disclosed delay meets regulatory standards.1 Supervisors can now reference the specific five categories when evaluating a company's justification for postponement.1 This should lead to more consistent enforcement across member states.1 The five additional legitimate interests give issuers more specified grounds they may rely on when considering a delay.1
For further information, ESMA’s Senior Communications Officer, Cristina Bonillo Olivares, is the designated contact.1 Stakeholders can reach out to her for clarification on how the new legitimate‑interest categories should be applied in practice.1 She can also provide guidance on updating internal disclosure procedures to meet the revised guidelines.1 ESMA encourages issuers to engage early with regulators to ensure smooth implementation of the changes.1
Structure
Who is connected to whom- 1ESMA
- regulated by →Fact
- enables →Fact
- requires →Fact
- drives demand for →Fact
- supplies →Fact
History
How it came to this- June 2026Timing rule changes for protracted processesIssuers are no longer required to disclose related inside information before the processes conclude.
- UndatedESMA finalizes revised guidelinesThe update adds new legitimate interests and removes those linked to protracted processes.
- Nowfive New legitimate interests that may justify delaying disclosure
Impact
Spreading outward, level by level- Level 1Issuer disclosure decisions
Issuers retain the duty to disclose inside information as soon as possible, but may delay when specific legitimate interests apply.1
Fact - Level 2Examples of grounds for delay
The added grounds include a public-authority request, the need for more information for market assessment, commercial opportunity risk, jeopardy to a key appointment, and direct prejudice involving another company in the same group.1
Fact - Level 3Guideline framework
Removing the protracted-process interests aligns the guidelines with the separate timing rule for those processes.1
Fact - Level 4Issuer compliance workload
The clearer categories and removal of the protracted-process disclosure requirement may reduce regulatory burden for issuers.
Analysis
Sources
What each source supportsWritten by AI from the sources listed below: every fact was checked word for word against its source, and inference is marked apart. How we write