Euronet and Fireblocks extend partnership to stablecoin-funded cards
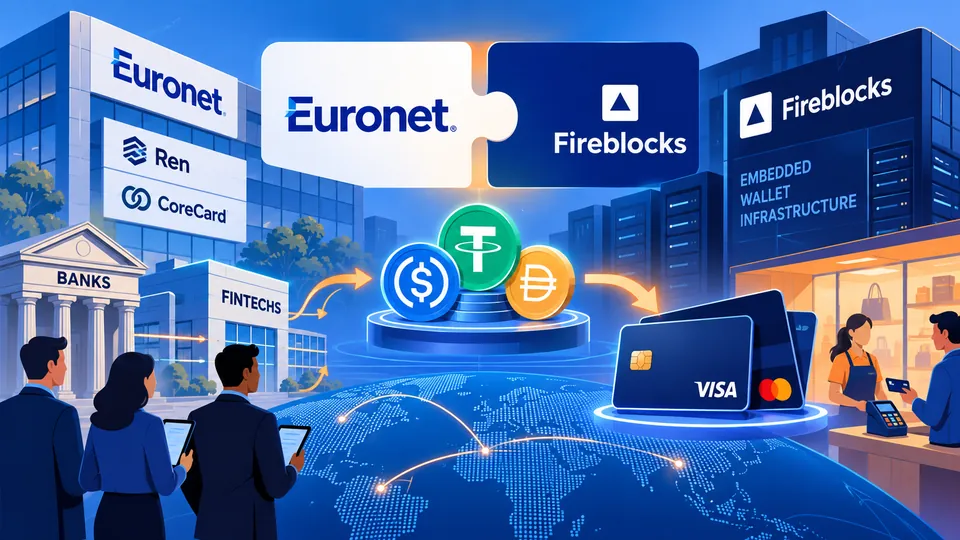
The service lets financial firms using Euronet’s Ren and CoreCard access Fireblocks’ embedded wallets for holding and transferring stablecoins. The companies say the white-label arrangement is intended to connect digital-asset balances with card payments and reach new markets.
Fireblocks facilitates more than $300 billion in stablecoin volume per month on average across its broader activity.3
Visa had more than 160 stablecoin-linked card programs live on its network in its fiscal second quarter of 2026.3
Euronet processed more than 20 billion transactions across its network in 2025.3
Story
From stablecoin infrastructure to card issuingEuronet and Fireblocks have extended their collaboration to let banks, fintech companies and other financial businesses build card products funded by stablecoins.12 The new offering is available to firms using Euronet’s Ren and CoreCard issuing services, which can now connect with Fireblocks’ wallet infrastructure.1 Those embedded wallets are designed to hold stablecoins and move them between parties, providing a digital-asset component alongside the card-issuing services.1 The arrangement is offered under each participating firm’s own branding and can be incorporated into its banking application or mobile wallet.1 The announcement describes an extension of an existing relationship, rather than the companies’ first joint service: they had previously worked together on cross-border payment settlement and pre-funding.12 Together, these details describe a service that combines card issuing already offered by Euronet with Fireblocks’ stablecoin wallets, rather than a standalone consumer card announced directly by the partners.1
In practical terms, the product links stablecoin wallet infrastructure to card programs that financial firms can present to their customers under their own names.13 The firms using the service are the banks, fintech companies and other financial businesses that issue or offer those programs through Ren and CoreCard.13 The proposed connection is between stablecoin balances and card networks, rather than a card offering that requires a separate conversion step before spending.3 The description says consumers and businesses can use such cards wherever cards are accepted, but it does not provide a count of customers or transactions for this new service.13 The partnership’s stated market objective is to take stablecoin card programs into additional markets and link digital assets with established card payments.1 That means the intended users span both the financial firms that create and distribute the programs and the consumers and businesses who may spend with them, though the facts provide no adoption total for either group.13
The companies’ previous collaboration addressed cross-border payments by providing settlement and pre-funding services, while the announced extension adds card issuing to their work together.12 That sequence places the new card service alongside an earlier payments use case, without specifying how many firms adopted the earlier services.1 Fireblocks supplies the wallet infrastructure in this arrangement, and the reported scale of its wider activity offers context for that role.13 The company works with hundreds of payments companies and handles an average of more than $300 billion in stablecoin volume each month.3 That monthly stablecoin-volume measure describes Fireblocks’ broader activity; it is not a reported volume for the Euronet card service.13 The contrast is between an established cross-border service and a newly announced card-issuing use case; the facts do not quantify how much either contributes to Fireblocks’ overall stablecoin volume.123
Fireblocks also secures $16 trillion in digital-asset transactions spanning more than 200 blockchains, according to the reported company figures.3 Those figures refer to Fireblocks’ wider digital-asset infrastructure and do not identify a share attributable to stablecoin-funded cards.13 Euronet’s reported scale is measured differently: it processed more than 20 billion transactions across its network in 2025.3 That is a network-wide transaction count, not a stated total for stablecoins or for this new issuing partnership.13 The figures therefore describe the companies’ existing reach and activity, not the number of cards or payments the new service has already produced.13 Because one measure covers digital-asset transactions and the other counts transactions across Euronet’s network, neither can be read as a direct estimate of this partnership’s expected card use.13
The broader card market provides another measure of activity: Visa had more than 160 stablecoin-linked card programs live on its network during its fiscal second quarter of 2026.3 Payment volume for those programs was nearly 200% higher year over year, a change reported for the Visa-network programs in that comparison.3 These counts and growth figures concern programs on Visa’s network, not the Euronet and Fireblocks service specifically.13 They indicate that stablecoin-linked card programs are already present on that network, while the new partnership is intended to enable financial firms to create offerings of their own.13 The available information does not give a direct comparison between the Visa programs and the firms that may use Ren or CoreCard.13 The Visa figures show reported activity in the wider market, but they do not establish how quickly firms using Euronet’s services will launch or how much their customers will spend.13
Goldi said stablecoins have moved from being mainly a way for Bitcoin traders to leave their holdings toward serving as a route from digital assets into global card payments.1 Goldi characterized stablecoins combined with global cards as an effective route out of digital assets, framing card access as central to their usefulness.1 That view is a company representative’s explanation of the opportunity, not a reported measure of consumer adoption or card spending.13 The service’s design is consistent with that stated aim: it puts embedded stablecoin wallets together with card issuing that financial firms can brand and distribute through their apps.1 The announcement does not specify how many banks or fintechs will launch programs, when launches will occur, or what spending limits they might set.1 Goldi’s assessment explains the partnership’s rationale, while the separate Visa figures offer evidence of existing market activity; neither supplies a forecast for adoption of this particular service.13
The potential audience is broad in category: the companies name banks, fintech firms and other financial businesses as prospective users of the issuing service.1 End users are described as consumers and businesses able to spend with stablecoin-backed cards where cards are accepted.3 The information does not say that every customer of a participating firm will receive a card, or that every card will support the same stablecoins.13 Nor does it give a total for participating financial firms, prospective cardholders or geographic markets already served by the new arrangement.1 The stated reach is therefore an intended expansion into new markets, while the reported program count belongs to Visa’s network and has a separate scope.13 The distinction matters for prospective users: the announcement identifies types of institutions and cardholders who could be served, but it does not establish which firms or customers will actually participate.13
The expansion comes as financial firms show reasons for caution about stablecoins, according to a Cleveland Federal Reserve Bank survey of 148 companies.1 Respondents cited satisfaction with existing payment methods, limited customer demand and insufficient familiarity with digital assets as reasons they were not adopting stablecoins.1 The survey presents those factors as findings among the companies it examined; it does not establish that all financial firms share the same view.1 A white-label service could let financial firms add an offering within their own apps, but the reported information does not show whether that design changes firms’ concerns.1 The survey’s findings and the companies’ launch plan thus describe different parts of the market: reluctance among surveyed firms and an infrastructure option for potential issuers.1 The survey results help explain why the availability of infrastructure alone does not demonstrate broad uptake: surveyed firms cited limited demand and familiarity alongside satisfaction with current methods.1
Other industry activity also points to efforts to develop stablecoin infrastructure: in July, a group of about 140 companies, including Visa and Stripe, assembled to launch the Open USD stablecoin.1 In August, Visa and Mastercard joined Circle Internet Group in backing the Arc initiative, which aims to support stablecoin activity in financial markets, real-time payments and agentic commerce.1 These initiatives are distinct from Euronet and Fireblocks’ card-issuing partnership, although each is part of the stablecoin activity described in the reporting.1 The partnership’s specific contribution is to join Euronet’s issuing services with Fireblocks’ stablecoin wallets in a white-label product for financial firms.13 Whether that structure brings more issuers into the market remains unreported; the available figures measure other activity, rather than adoption of this new service.13 Taken together, the reported initiatives show activity across stablecoin infrastructure and card programs, but their separate scopes do not indicate how many issuers this particular partnership will attract.13
History
How it came to this- Last yearEarlier cross-border payments partnershipEuronet and Fireblocks previously worked together on settlement and pre-funding services for cross-border payments.
- AnnouncementPartnership extended to card issuingThe companies announced an extension that connects Euronet’s Ren and CoreCard issuing services with Fireblocks’ stablecoin wallet infrastructure.
- JulyOpen USD initiativeA consortium of about 140 companies, including Visa and Stripe, convened to launch the Open USD stablecoin.
- AugustArc initiative backedVisa and Mastercard joined Circle Internet Group to support the Arc initiative for stablecoin activity.
- NowLaunched Euronet–Fireblocks stablecoin-funded card issuing
Impact
Spreading outward, level by level- Level 1Financial firms issuing cards
Firms using Euronet’s Ren and CoreCard services can access Fireblocks’ embedded wallets to hold and transfer stablecoins, with the offering available as a white-label solution for their own apps.1
Fact - Level 2Consumers and businesses spending
Stablecoin-backed cards connect balances directly to card networks, removing a conversion step and allowing consumers and businesses to spend wherever cards are accepted.3
Fact - Level 3Broader card-market activity
Visa-network stablecoin-linked card programs offer context for the market, but their reported count and payment-volume growth are not figures for this Euronet and Fireblocks service.3
Fact - Level 4Potential issuer adoption
The partnership aims to bring programs into new markets, but surveyed firms’ reported satisfaction with existing payment methods, limited customer demand and lack of familiarity may constrain uptake; the facts do not show whether this offering changes those concerns.
Analysis
Sources
What each source supportsWritten by AI from the sources listed below: every fact was checked word for word against its source, and inference is marked apart. How we write